Keeping Nigeria's Payments Safe Is Now Big Business
Nigerians moved more than ₦1 quadrillion electronically in 2024. Fraud losses halved last year, new rules took effect in July, and protecting all that money has become an industry in its own right.
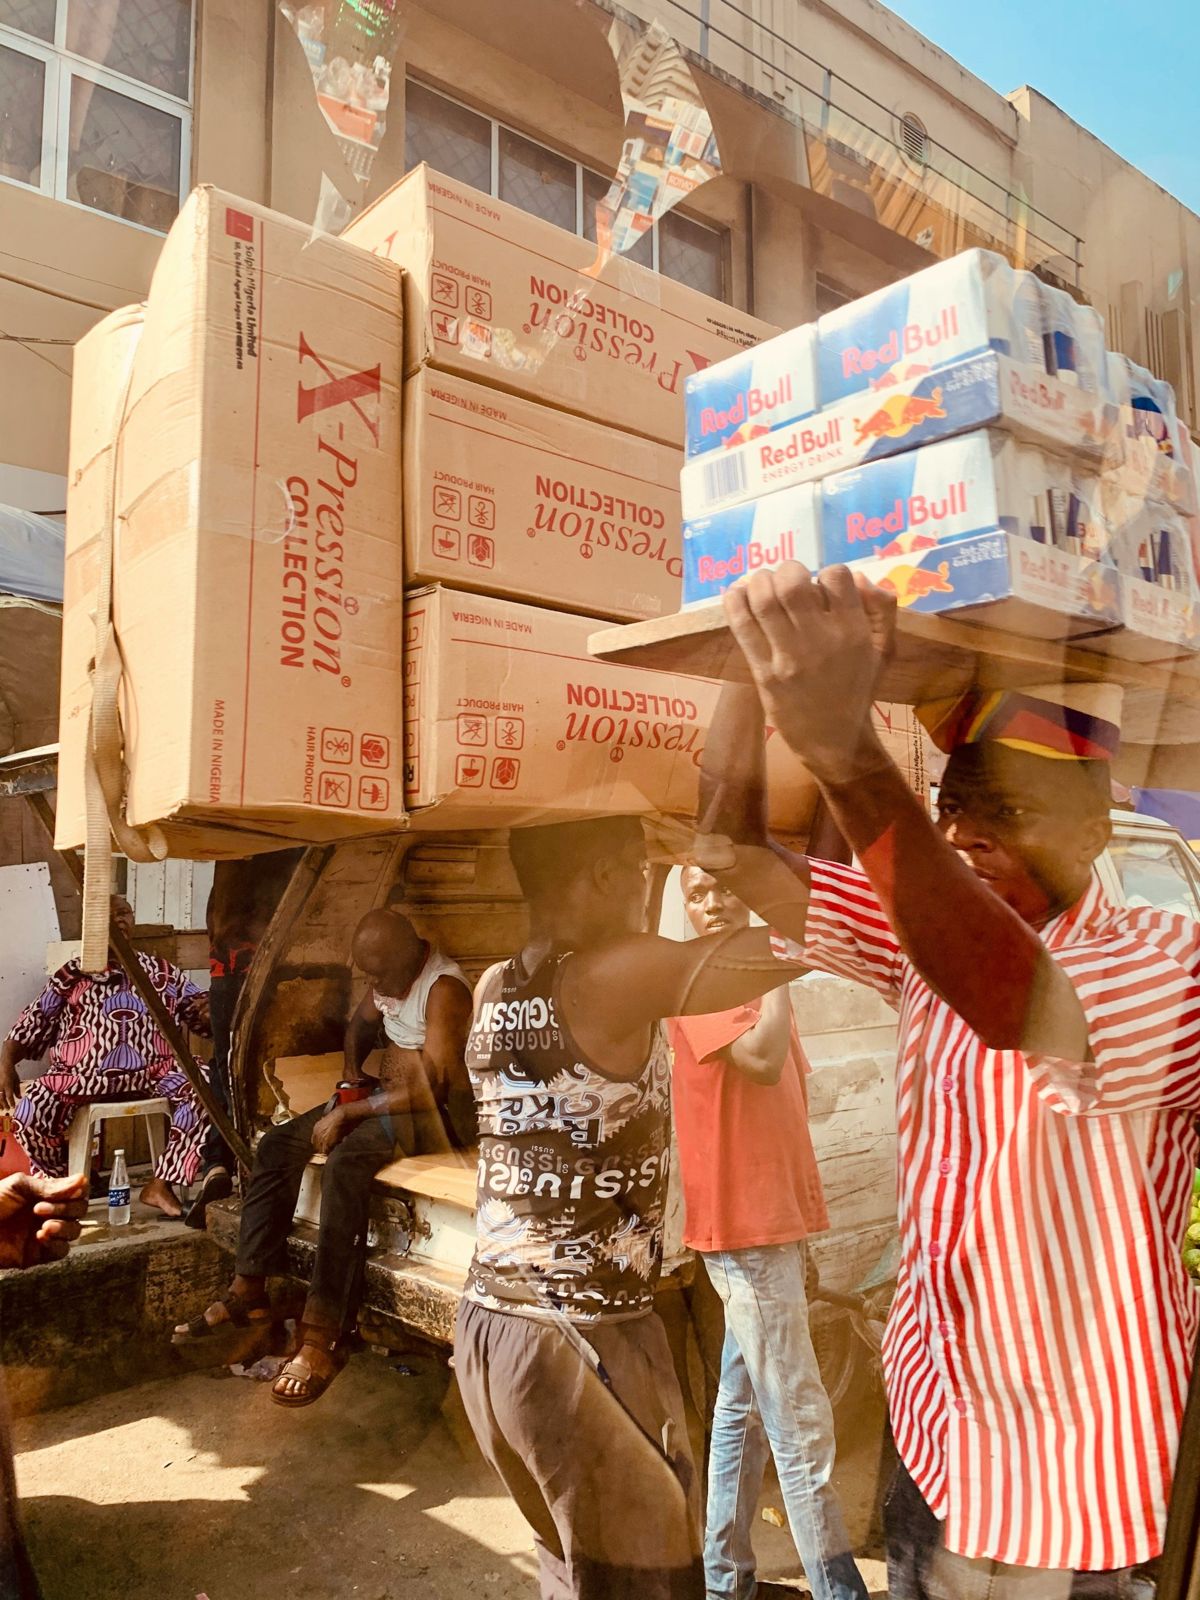
Photo: Mary on Unsplash
Walk into a shop in Lagos and the familiar exchange of cash for goods is increasingly sharing space with something much simpler. A customer asks for the shopkeeper's account details, opens a banking application and transfers the money directly. A payment notification arrives, the transaction is confirmed and both people get on with their day.
Behind that relatively ordinary moment sits one of Africa's largest digital payment systems, processing billions of transactions each year and supporting a growing network of banks, fintech companies, merchants and small businesses.
The scale of its development is considerable. According to the Nigeria Inter-Bank Settlement System (NIBSS), the value of electronic payments processed through its infrastructure increased from approximately ₦600 trillion in 2023 to ₦1.07 quadrillion in 2024. Transaction volumes rose from 9.7 billion to around 11.2 billion over the same period.1
These figures tell the story of a financial system undergoing significant change. Digital payments have become an increasingly important part of how Nigerians conduct business, but their expansion has also created greater demands for security, reliability and the systems needed to move money safely.
For banks and fintech companies, the challenge is no longer simply making digital payments possible. It is keeping those payments fast and accessible while protecting customers against fraud, account compromise and the consequences of technological failure.
In an October 2026 interview with Nigerian technology publication Techeconomy, Chinwe Uzoho, Regional Managing Director for West Africa at payments technology company Network International, described the wider transformation taking place within the banking industry.
"Modernisation is no longer viewed as a technology project," she explained,2 describing how banks increasingly connect infrastructure investment with commercial growth and customer experience.
The distinction is important. Banks are not simply replacing ageing computers or installing new security software. They are changing the underlying infrastructure used to process transactions, connect with fintech providers and deliver financial services to customers.
According to Uzoho, institutions across West Africa are increasingly investing in cloud-enabled platforms, modern payment systems, application programming interfaces and real-time processing capabilities. Rather than replacing their entire infrastructure in one expensive and potentially disruptive exercise, many banks are introducing improvements gradually while keeping existing services operational.
For customers, much of this work remains invisible. The expectation is that a payment should arrive within seconds, regardless of the technology operating behind it. For businesses, however, the reliability of that infrastructure can directly influence whether they can trade normally, pay suppliers or receive money from customers.
This creates an unusual commercial challenge. Banks are expected to process increasingly large volumes of transactions almost instantly, while also identifying suspicious activity before money reaches fraudulent accounts.
Nigeria's experience shows why achieving both has become such an important part of the cybersecurity industry.
In January 2026, NIBSS reported that actual losses from digital payment fraud had fallen from ₦52.26 billion in 2024 to ₦25.85 billion in 2025, a reduction of approximately 51%.3
The figures were presented by NIBSS Managing Director and Chief Executive Officer Premier Oiwoh at the Nigeria Electronic Fraud Forum in Lagos.
They represent a significant decline, although the comparison requires some context. NIBSS explained that the particularly high losses recorded in 2024 had been heavily influenced by one incident involving approximately ₦31.1 billion at a single institution.
The number of reported fraud cases also declined, by about 4%, to 67,518 in 2025.3
Taken together, the figures indicate that recorded fraud losses and reported incidents fell during 2025. They do not establish that every type of fraud became less common, nor do they prove that particular technologies were responsible for the improvement.
Indeed, NIBSS continued to identify social engineering, account compromise and insider involvement as significant concerns. Oiwoh described insider abuse as the greatest current threat. NIBSS also warned about gaps in incident reporting, which fell by 34% in the last quarter of 2025, making it harder for institutions to identify patterns and coordinate investigations.3
The continuing challenge is particularly visible in the way fraudsters exploit ordinary financial behaviour.
A small business owner might receive a fraudulent payment notification, an individual might be persuaded to transfer money to someone impersonating a legitimate seller, or an attacker might attempt to gain control of a customer's banking account.
These attacks do not always require sophisticated technical intrusions. Many depend on deception, misplaced trust or weaknesses in identity verification.
For financial institutions, that creates a difficult balance. Security measures need to identify potentially fraudulent behaviour without routinely preventing legitimate customers from accessing their money.
Banks and fintech companies are increasingly using automated transaction monitoring, behavioural analytics and machine learning to help address this problem.
Such systems can examine payment activity for unusual patterns, including unexpected account behaviour, changes in the devices used to access services or transfers that differ substantially from a customer's established activity.
In her Techeconomy interview, Uzoho described how Network International works with financial institutions using fraud prevention technologies, including FICO Falcon Fraud Manager, which incorporates artificial intelligence, machine learning and behavioural analysis.2
"The challenge for banks today is not simply preventing fraud," she said, before explaining the importance of avoiding unnecessary disruption to customers.
Her comments reflect the commercial interests of a company providing payment technology, but they also highlight a problem facing the wider financial services sector. A security system that routinely blocks legitimate transactions can frustrate customers, increase support costs and undermine confidence in digital services.
A system that fails to identify suspicious behaviour creates a different set of risks.
For banks, the value of fraud detection increasingly depends on whether it can make reliable decisions quickly enough to operate within modern payment systems.
The Central Bank of Nigeria has been strengthening the regulatory requirements surrounding these activities.
Security standards that took effect on 1 July 2026 require financial institutions to deploy real-time enterprise fraud monitoring and verify the identity of customers opening or reactivating accounts online against national identity and bank verification databases.4
The measures also restrict mobile banking applications to one registered device at a time. For new accounts, and when an application is activated on a new device, a transaction limit of ₦20,000 applies for the first 24 hours.4
Additional provisions require stronger authentication when customers first log in on a new device and allow customers to set their own transaction limits.4
These requirements demonstrate how cybersecurity is becoming part of the design and operation of banking services, rather than a separate function introduced after a product has been launched.
They also create commercial opportunities for companies developing fraud detection, digital identity verification, security monitoring and payment infrastructure.
Financial institutions must adapt their products and operational processes to meet regulatory expectations, while technology suppliers compete to provide the systems that make compliance and fraud prevention possible.
The Central Bank has also been considering how responsibility should be allocated when customers are deceived into authorising payments themselves.
In November 2025, it published draft guidelines addressing authorised push payment fraud, where criminals persuade victims to transfer money under false pretences.5
The proposals included requirements for financial institutions to maintain accessible fraud reporting channels, investigate incidents and consider reimbursement where specified conditions are met.
Importantly, these were consultation proposals rather than final rules. Their publication nevertheless demonstrated the regulator's interest in examining the responsibilities of banks and payment providers when fraud occurs.
For Nigerian businesses, the consequences of these developments extend beyond financial institutions.
Small retailers, independent traders and service providers increasingly rely on electronic payments to operate. While digital transactions can offer convenience and reduce some of the practical difficulties associated with cash, they also introduce dependencies on banking applications, payment networks and telecommunications infrastructure.
When a transaction fails, a customer may be unable to complete a purchase. When a payment is fraudulent, a merchant can lose stock or revenue. When systems become unavailable, normal business activity may be interrupted.
For small enterprises operating with limited financial reserves, these problems can be particularly disruptive.
The modernisation of payment infrastructure is therefore connected to a much wider economic question: whether businesses can depend on digital financial services as their use continues to expand.
Uzoho's interview also highlighted the relationship between modern payment systems and financial inclusion. She identified unreliable electricity, limited connectivity, insufficient digital literacy and difficulties accessing affordable devices as continuing barriers in parts of West Africa.2
These challenges show why the development of a digital financial system cannot be measured solely by the total value of transactions passing through it.
A bank may have sophisticated fraud detection technology, but customers still need reliable access to its services. A business may be able to accept electronic payments, but the benefits become less useful if connectivity or electricity repeatedly interrupts transactions.
The continuing expansion of digital finance therefore places demands on infrastructure, consumer protection and cybersecurity simultaneously.
It also raises questions about the future of Nigeria's technology industry.
Companies providing payment processing, fraud analytics, identity verification and secure financial infrastructure are operating in a market where demand is being shaped by commercial growth and regulatory requirements.
Local fintech businesses need to demonstrate that their systems can handle large transaction volumes while meeting increasingly detailed security expectations. Banks must also work with technology providers capable of integrating new capabilities into older infrastructure without disrupting essential services.
As more Nigerian businesses conduct transactions digitally, there may be opportunities for providers offering affordable and reliable technology adapted to local operating conditions.
Cross-border commerce adds another dimension. Companies trading across West Africa need payment services that can operate between different institutions, currencies and regulatory environments.
Improving interoperability and security can support those activities, although the benefits depend on cooperation between providers and the practical availability of services to businesses.
Nigeria's experience is also relevant beyond its borders. Across Africa, digital financial services are changing how individuals and businesses access money, while financial institutions face the challenge of managing increasingly interconnected technology.
The Nigerian figures offer an important perspective on that development.
The scale of electronic payments has expanded substantially, while reported fraud losses declined in 2025. Banks and fintech companies are investing in modern infrastructure, and regulators are introducing more detailed security expectations.
These developments should not be interpreted as proof that Nigeria has solved digital payment fraud. The figures show that substantial financial losses continue to occur, while the technologies used by both financial institutions and criminals continue to develop.
What they do illustrate is how cybersecurity is becoming part of the commercial infrastructure supporting a major digital economy.
For Nigerian banks, fraud prevention is now closely connected to customer experience, operational reliability and regulatory compliance. For businesses, secure payments affect the confidence with which they can trade. For cybersecurity companies, the evolving financial system represents a market for specialist technology and services.
Nigeria's digital payments industry has already demonstrated its ability to process transactions at enormous scale. The continuing task for the businesses and institutions operating it is to ensure that the systems moving that money remain reliable, secure and accessible to the people depending on them.
Corrections: none. If you spot an error, tell us and we will correct it openly.